Outsourced Sales Australia: Calculating Your True Cost Per Sales-Qualified Lead Realistically
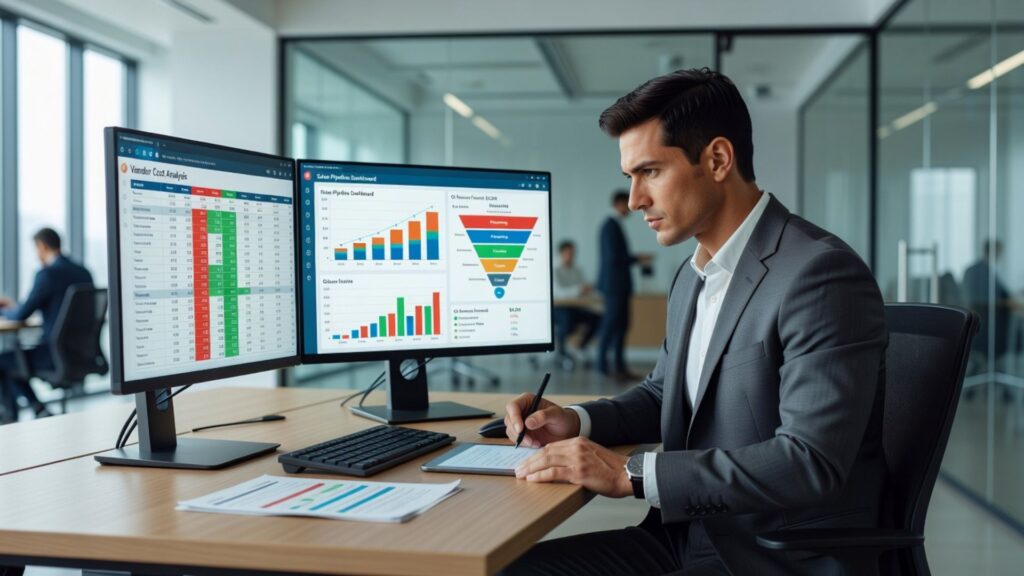
The cost per sales-qualified lead is one of the most useful metrics in revenue operations, and one of the most consistently miscalculated. The number that most sales and marketing teams report as their cost per SQL is typically the media spend or agency fee divided by the number of leads tagged as qualified. This calculation omits several categories of cost that are material to the true figure, and the gap between the reported number and the actual number is often large enough to change strategic decisions if it were properly understood.
What the Standard Calculation Misses
The technology stack required to run a lead generation programme is a cost that is rarely allocated to cost per SQL calculations. CRM licences, marketing automation platforms, sales engagement tools, data intelligence subscriptions, and the infrastructure required to track and attribute leads all carry monthly costs that are directly associated with the programme generating the leads. Distributing these costs across the leads produced provides a more accurate picture of the true investment.
Internal time is the second major category of omission. Sales development representatives who qualify and follow up on leads, marketing managers who manage campaigns and review results, sales managers who review pipeline quality, and any other internal resources dedicated to the lead generation and qualification process all carry a cost that belongs in the cost per SQL calculation. Calculating this at an hourly cost rate based on salaries and on-costs, multiplied by the actual time spent on programme-related activities, provides the labour component of the true cost.
The disqualification rate is the third dimension that affects the true cost per SQL. If a programme generates fifty leads and twenty are qualified as SQL, the cost per SQL is not the programme cost divided by fifty but the programme cost divided by twenty, adjusted for the time spent qualifying and rejecting the thirty disqualified leads. A programme with a high lead volume but a low qualification rate may have a higher true cost per SQL than a programme with lower volume but higher qualification rates, even if the headline cost per lead appears lower.
The Comparison Problem With Outsourced Programmes
When evaluating sales outsourcing services company proposals, applying the same rigorous cost calculation to the outsourced alternative as to the internal programme creates a genuinely comparable basis for the make-versus-buy decision. Outsourced programmes typically include the equivalent of several internal cost categories within their service fee, including technology, management overhead, and the salary equivalent of the SDR function.
A surface comparison of the outsourced programme fee against the internal media spend will almost always favour the internal programme on a cost per lead basis. A comparison that includes the full internal cost stack frequently reveals that the outsourced programme, while more expensive per lead, is more cost-effective per SQL and significantly more cost-effective per closed deal when the opportunity cost of internal management time is properly accounted for.
Setting Realistic Targets
Outsourced sales australia programme targets that are set without reference to realistic benchmarks for the industry category, average deal size, and sales cycle length produce either disappointing results against inflated expectations or misleading conclusions about programme performance against targets that were too conservative. Industry benchmarks for cost per SQL vary significantly by sector, with complex enterprise software programmes typically showing costs per SQL in the thousands of dollars and higher-volume transactional programmes showing costs in the hundreds.
Setting targets that reflect these benchmarks, and building a measurement framework that captures the full cost stack rather than a partial view, produces data that can drive genuine improvement decisions rather than optimistic reporting that obscures where investment should be redirected.