How Credit Score Impacts Personal Loan Approval and Interest Rates
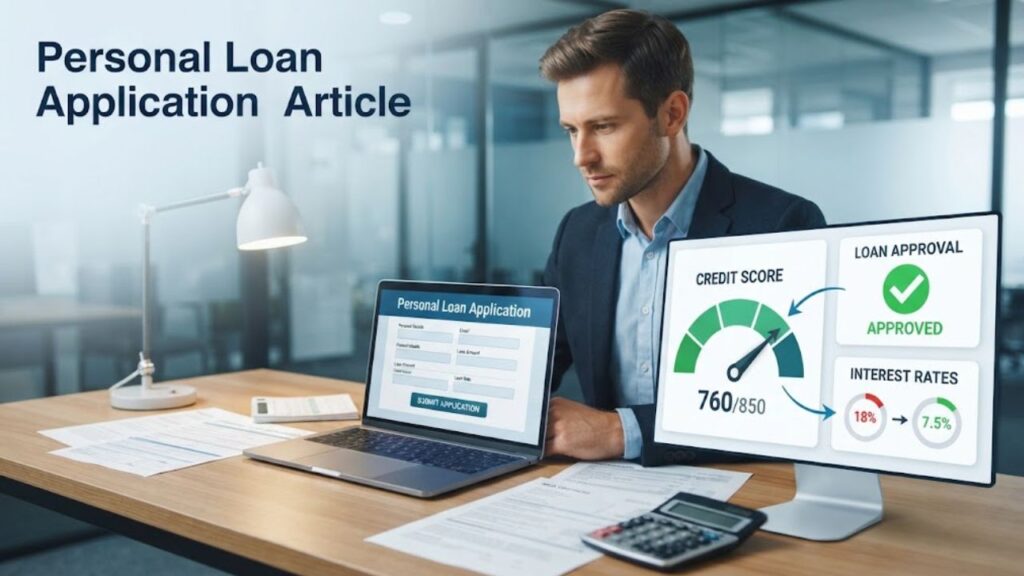
A credit or CIBIL score is basically a number between 300 and 900, issued by credit bureaus such as TransUnion CIBIL, amongst others. It is the first thing a lender checks as soon as you apply for a personal loan. A score above 750 is deemed excellent and can get you a good deal in terms of interest rates (often under 11%). However, a score below 650 is considered low, and you might need a co-applicant to get your loan approved. Plus, the chances of rejection here are quite high. Income, existing debt, and employment type matter too, but credit score decides the door you walk through first.
Quick Reads
- A CIBIL score above 750 is regarded as excellent, in which the approval odds are high, and interest rates are low.
- Credit scores below 600 get declined by most banks. However, some NBFCs might still lend to you, but at steep rates.
- Income stability, Fixed Obligation to Income Ratio (FOIR), and recent credit inquiries matter almost as much as the score itself.
- A 60- to 90-day cleanup of card balances and overdue EMIs can shift your score bracket before you apply.
Ever wondered why two people applying for the exact same loan amount walk away with completely different outcomes? One gets approved in a day at 10.5%. The other gets a flat no, or worse, a “yes” buried under a 20% interest rate. The difference usually isn’t income. It isn’t even the bank they picked. It’s a three-digit number sitting quietly in a CIBIL report, one most people never check until it’s too late. Your credit score decides the terms before you’ve even finished filling out the form.
Credit Score: What Does it Mean and Why it Matters?
A three-digit number between 300 and 900 is a credit score, which basically summarizes your past ability to repay a loan or credit to the lender. It’s not a mystery number pulled from thin air. It’s calculated from your repayment history, credit card usage, and loan inquiries.
Credit score refers to the numerical output generated by a credit bureau, such as TransUnion CIBIL, Experian, or Equifax, based on years of your borrowing behavior.
In India, CIBIL is the most widely used bureau, which the majority of lenders utilize to pull out your CIBIL report before processing your loan application. A score below 600 is considered weak, 650 to 699 is counted as fair, 700 to 749 is a good one, and 750 to 900 is excellent.
One more thing to notice here is that this score exists before you even fill out the loan form. Lenders pull it the moment you apply. So by the time you’re sitting across from a loan officer (virtual or otherwise), the decision is already half made.
Does Credit Score Influence Personal Loan Approval?
Credit scores do influence your loan application. For lenders, this score is used as a first filter, looked way before your income documents. If you have a credit score below 600, the chances are most banks won’t even touch your application.
Between 650 and 749, you’re in workable territory; approval is possible but expect conditions. Cross 750, and you’re the applicant lenders actually want.
Now the question here is: what if you have a score below 600? If so, NBFCs or fintech lenders that work with scores as low as 550 can be your point of contact, but they balance that risk with higher interest rates and lower loan caps. So, it’s not that a weak score locks every door. It just leaves you fewer, and pricier, ones.
| Credit Score Range | Creditworthiness | Approval Likelihood |
| Below 600 | Poor | Very low, most banks decline |
| 600–649 | Doubtful | Low, may need a co-applicant |
| 650–699 | Fair | Possible, often with higher rates |
| 700–749 | Good | High |
| 750–900 | Excellent | Very high, best terms available |
Some known NBFCs, such as Finnable, also offer collateral-free personal loan options, where borrowers can get up to ₹10 Lakhs within a few hours of applying, subject to terms and conditions. In addition, borrowers can calculate their personal loan limit by adding a few details, such as salary, current credit score, and monthly EMI (if any).
Can Your Credit Score Change Your Personal Loan Interest Rate?
Take credit score as the lender’s shorthand for risk, used to calculate the interest rate you will be offered. A high score equals low interest rates, and a low score equals higher interest rates.
- A score above 750 gets you money at rates under 11% per annum with major banks.
- Weaker scores (550 to 649, maybe) place lenders in a doubtful position, where they might be willing to lend but starting around 10.75% and climbing well past that.
- Some banks offer personal loans up to ₹5 lakh, with rates commonly starting near 12% for salaried applicants.
The gap is huge, since personal loans carry no collateral. In a case where you default, the lender has nothing to recover their money except legal recourse. A strong score is the only real insurance they get, so they price accordingly.
What Other Factors Affect Approval Besides Credit Score?
Credit score matters most, but it’s not the only variable. Lenders also weigh your income stability, existing debt load, employment type, and even your city of residence.
- Income and job type: Salaried employees at registered firms have a higher and faster chance of approval than self-employed applicants.
- Fixed Obligation to Income Ratio (FOIR): If your existing EMIs already eat up 50% or more of your monthly income, lenders get cautious regardless of your score.
- Credit utilization: Maxing out your credit cards each month, even if you pay on time, can quietly drag your score down.
- Recent credit inquiries: Applying to five lenders in a month looks desperate to an algorithm. Space out your applications.
- Existing relationship with the lender: A borrower with a salary account at major banks often gets pre-approved offers that skip some of the usual scrutiny.
Checklist: Before You Apply for a Personal Loan
- Check your CIBIL score at least two weeks before applying (free checks are available through the CIBIL website or most banking apps)
- Maintain credit card balances at under 30% of your total limit
- Clear or reduce any overdue EMIs
- Avoid simultaneously applying to multiple lenders
- Keep income proof, ID, and address documents ready and current
- Compare at least three lenders’ rates before signing; don’t take the first offer
Where This Leaves You
If you’re planning to apply for a personal loanin the next few months, start with your score, not the loan comparison sites. A 60- to 90-day window to pay down card balances and clear small overdue amounts can genuinely shift you from the “fair” bracket into “good,” and that shift alone can save you several percentage points in interest over the life of the loan. Check your score first. Everything else follows from there.