How to Plan for Unexpected Medical Bills Without Derailing Your Finances
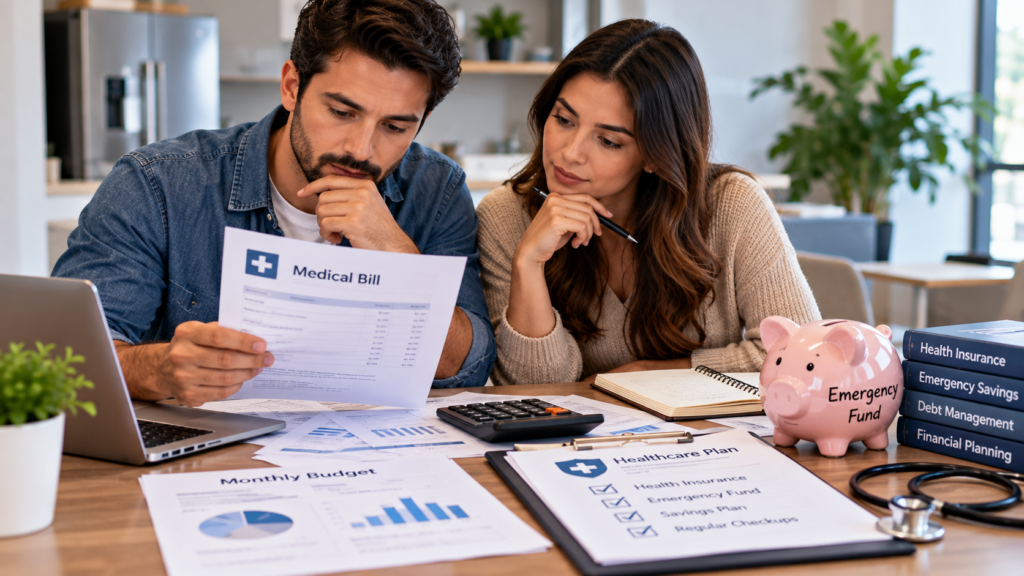
Nobody budgets for a hospital stay. Medical costs tend to arrive on their own schedule, usually at the worst possible time, and even people with solid savings and insurance can find themselves scrambling when the bills start stacking up. A surgery, a specialist referral, a few days in a ward, follow-up visits, medication: each line item looks manageable until you add them together.
The good news is that medical expenses are one of the few financial shocks you can prepare for in a fairly practical way. Here’s how to think about it before, during, and after the bill lands.
Understand What Your Coverage Actually Pays For
The most common mistake is assuming “I have insurance” means “I won’t pay anything.” In practice, coverage usually comes with deductibles, co-payments, claim limits, and exclusions, and some insurers require you to pay upfront and claim reimbursement later. That gap between what a bill costs today and what you get back weeks from now is where a lot of people get caught short.
If you live in Singapore, the layers typically include national schemes such as MediShield Life, personal savings in MediSave, and, for those who have one, an Integrated Shield Plan on top. Each pays differently depending on the type of treatment, the ward class, and whether the procedure is covered at all. Spending an hour reading your own policy summary, before you need it, is one of the highest-value financial tasks you can do. Know your deductible, your co-payment percentage, your annual limit, and what’s excluded.
Know the Costs Before You Commit
For planned treatment, ask for a written cost estimate before the procedure. Hospitals and clinics can usually give you a range, and some will break it down into surgeon’s fees, anaesthetist’s fees, ward charges, and consumables. Two things are worth asking every time: what your insurance is expected to cover, and what you’ll be expected to pay out of pocket, and when.
It’s also worth asking whether there’s a lower-cost route to the same outcome. A different ward class, a day-surgery option instead of an overnight stay, or a subsidised clinic for follow-up visits can change the final number noticeably without changing the quality of care.
Build a Small, Separate Medical Buffer
An emergency fund is the cheapest way to absorb a medical bill because it carries no interest. If you’re building one from scratch, it helps to think of a medical buffer as its own line item rather than a vague share of general savings. Even a modest amount set aside regularly can cover a co-payment, a deductible, or the upfront portion of a claim.
A realistic target is whatever your typical deductible and co-payment would be for a hospital stay, plus a little extra for transport, medication, and the lost income that often comes with time off work. It won’t cover a catastrophic event, but it will cover the more common ones.
Use Every Available Support Before Borrowing
Before turning to any form of credit, check what else is available. Payment plans offered directly by hospitals or clinics can spread a bill over several months, often without interest. Government assistance schemes exist for those who qualify, and hospital financial counsellors can walk you through them. Family contributions, employer benefits, and CPF or MediSave withdrawals for approved treatments are other avenues worth exploring first.
These options are almost always cheaper than commercial borrowing, so it makes sense to exhaust them, or at least confirm what they’d cover, before committing to a loan.
When Short-Term Borrowing Makes Sense
There are situations where support schemes and savings aren’t enough or aren’t fast enough. A bill that has to be paid before discharge, treatment that’s not covered by insurance, an elderly parent’s medical expense that needs settling now: in moments like these, short-term borrowing can be a reasonable tool, provided it’s done carefully.
In Singapore, a licensed medical bills loan from a registered moneylender is built for this kind of timing gap. Licensed lenders operate under the Moneylenders Act, with interest capped at 4% per month, disclosed fees, and a written contract before any money changes hands. The aim is to cover the immediate cost so you can focus on recovery, then repay on a schedule you’ve agreed in advance, rather than letting an unpaid bill escalate.
Whatever lender you consider, a few habits protect you:
- Check the licence. Confirm the lender appears on the Ministry of Law’s Registry of Moneylenders before sharing any personal details.
- Borrow only what the bill requires. It’s tempting to round up, but every extra dollar accrues interest.
- Read the repayment terms. Know the instalment amount, the tenure, and what happens if you miss a payment before you sign.
- Be wary of unsolicited offers. Licensed moneylenders can’t cold-message you on WhatsApp, SMS, or social media, and no legitimate lender asks for fees before approval.
Don’t Forget the Hidden Costs of Being Unwell
Hospital bills are only part of the picture. Transport to appointments, extra childcare or eldercare, special diets, medication, and lost income all add up. When you’re estimating how much a medical event could cost, include these indirect expenses, because they’re often what turn a manageable bill into a genuine strain.
Make a Plan While You’re Healthy
The best time to prepare for a medical expense is when you don’t have one. Review your insurance coverage once a year, keep a small medical buffer topped up, and make a note of the payment options and assistance schemes available to you. If a large bill does arrive, the combination of preparation and knowing your options will make the difference between a stressful few weeks and a financial setback that lasts for years.
Medical bills are rarely predictable, but your response to them can be. Know what your coverage pays, ask for estimates in writing, lean on lower-cost support first, and, if you do need to borrow, choose a licensed lender with terms you understand and can comfortably repay.