How South Africans Are Rethinking Short-Term Borrowing in a Tight Economy
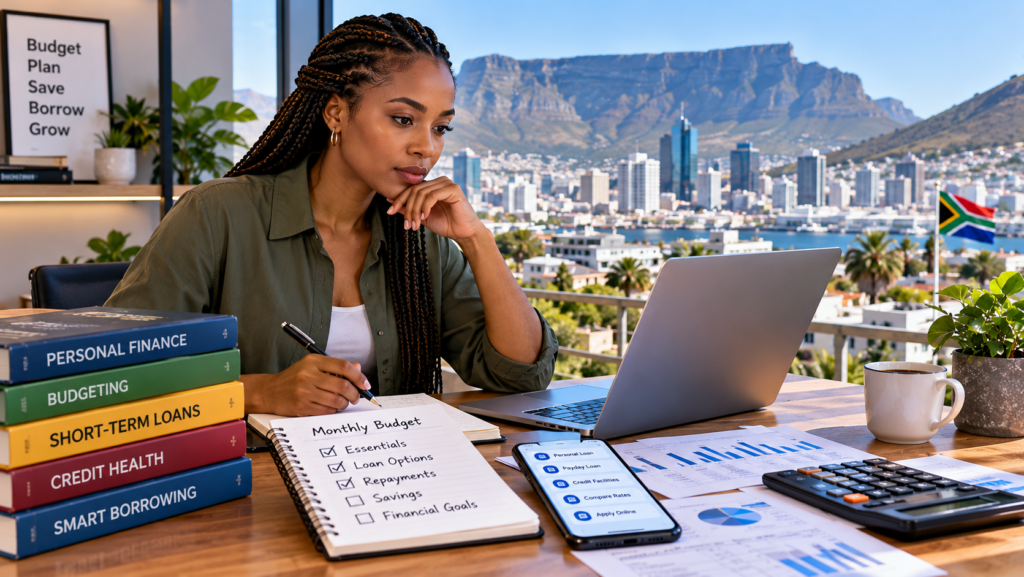
Rising living costs have pushed many South African households to reconsider how they manage unexpected expenses. Short-term credit options have become a common topic of conversation, not because borrowing is new, but because the way people access funds has changed so dramatically in recent years.
Why Short-Term Loans Remain Popular
Unexpected costs rarely wait for payday. A car that breaks down, a medical bill, or a sudden school expense can throw a household budget off balance within days. For many South Africans, traditional bank loans are not always practical, especially when approval processes take time or require extensive paperwork. This has made short-term lenders an attractive alternative, particularly for people who need a quick decision rather than a long-term credit relationship.
The appeal lies in flexibility. Short-term loans are typically smaller in size and repaid over a matter of weeks or months, which makes them easier to plan around compared to larger, long-term debt. That said, borrowers are increasingly aware that convenience should never come at the cost of understanding the full terms of an agreement, including interest rates and repayment schedules.
The Shift Toward Digital Lending Platforms
Smartphone usage and improved internet access across South Africa have reshaped how people borrow money. Where loan applications once meant standing in queues or waiting days for a response, many platforms now process requests almost entirely online. This shift has been particularly significant for people in rural or underserved areas who previously had limited access to formal credit options.
Digital platforms such as loan4debt.co.za reflect this broader trend, offering a structured way for applicants to submit information and receive feedback without needing to visit a physical branch. The convenience of digital applications has also encouraged more transparency, as borrowers can compare terms and conditions before committing to an agreement, something that was far more difficult in the past when information was scattered or inconsistent between lenders.
This move toward online lending has not eliminated the need for caution, however. Financial literacy remains essential, and South Africans are encouraged to read loan agreements carefully, understand the total repayment amount, and confirm that a lender is registered with the National Credit Regulator before proceeding.
- Faster application processes compared to traditional banks
- Greater accessibility for people without a nearby branch
- Improved ability to compare lenders and terms online
- Increased responsibility on borrowers to verify legitimacy
Speed as a Deciding Factor
One of the clearest shifts in borrower behaviour is the demand for speed. Many applicants are not just looking for a loan, they are looking for a solution that fits into an already stressful situation. This has led to a rise in services promoting an instant cash loan in 5 minutes, a concept that would have seemed unrealistic a decade ago but is now part of everyday financial vocabulary for many South Africans.
While speed is a genuine benefit, it also places more responsibility on borrowers to make quick but informed decisions. Automated systems can approve applications rapidly by checking basic eligibility criteria, but the final responsibility for repayment still rests with the borrower. This balance between convenience and accountability is shaping how financial education is being delivered alongside these services, with more platforms including clear explanations of fees, interest, and repayment terms directly within the application process.
A Changing Relationship With Credit
South Africa’s lending landscape is evolving alongside its digital infrastructure. As more people turn to online platforms for short-term financial relief, the emphasis is shifting from simply accessing credit to understanding it fully before signing on the dotted line. This evolving relationship between speed, accessibility, and responsibility will likely continue to define how short-term borrowing develops across the country in the years ahead.